The short answer
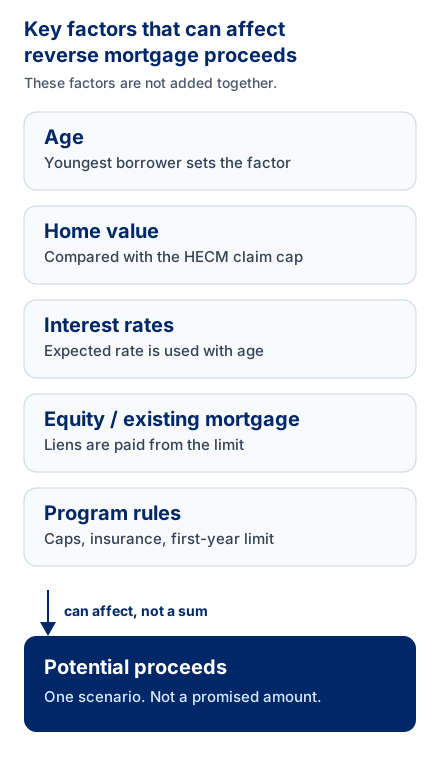
On an FHA-insured Home Equity Conversion Mortgage, the lender starts with a principal limit. That limit comes from the youngest borrower's age, an expected interest rate, and the lesser of the home's value and the national maximum claim amount. Money you actually receive is what remains after required payoffs and upfront costs.
You still own the home. A reverse mortgage does not hand you the full value of the house.

What a principal limit is
The principal limit is the ceiling for that HECM before payoffs. HUD publishes principal limit factors by age and expected rate. This website looks those factors up in the calculator. It does not print a table of "you get this percent at this age," because a factor is not the cash you take home.
The 2026 maximum claim amount
For HECM calculations on this site, the maximum claim amount is $1,249,125. The calculator uses the lesser of your entered home value and that amount. The figure is stored in the site's 2026 limits file and is tied there to Mortgagee Letter 2025-22. HUD can change the cap. Confirm the letter that applies to a new case number before you rely on it.
If your home is worth more than the cap, a proprietary reverse mortgage is sometimes discussed. This page does not quote proprietary proceeds. Those programs are not the HECM calculator.
Existing mortgages come out first
A reverse mortgage generally pays off the mortgages and other liens on the home at closing. A homeowner with a large remaining balance can have a principal limit that mostly goes to that payoff, with little cash left. That is an equity question as much as a borrowing question: how equity is counted.
Age and the expected rate
Borrowers must be at least 62. When more than one borrower is on the loan, the youngest borrower's age is the one used for the factor. A lower expected rate generally pairs with a higher factor, and an older youngest borrower generally pairs with a higher factor. Those are directions in the HUD table, not a quote. The age rules and the principal-limit explanation cover this without a percentage chart.
Costs reduce the cash
Initial mortgage insurance, an origination fee, and other closing charges are usually financed. Financing them means they are paid from the principal limit, so available cash is lower. See reverse mortgage costs and fees.
A labeled illustration
Hypothetical example
Two homeowners can have the same home value and very different cash. One owes little and is older. The other still has a large mortgage, or the youngest borrower is closer to 62. The second file can show a principal limit that is mostly used to pay off the existing loan. Do not treat either case as a typical result.
What this page does not promise
Nothing here is a loan offer or a statement that you qualify. Run your own numbers in the reverse mortgage calculator, then have a counselor and a licensed originator review the file. HECM borrowers complete HUD-approved counseling before closing.
Last updated 2026-10-01. This content is for education. It is not legal, tax, or financial advice and is not a commitment to lend.