The short answer
The Home Equity Conversion Mortgage is for homeowners age 62 or older. Every borrower on the loan has to meet that age. Someone younger than 62 is not a HECM borrower, even if they live in the home or are married to the applicant.
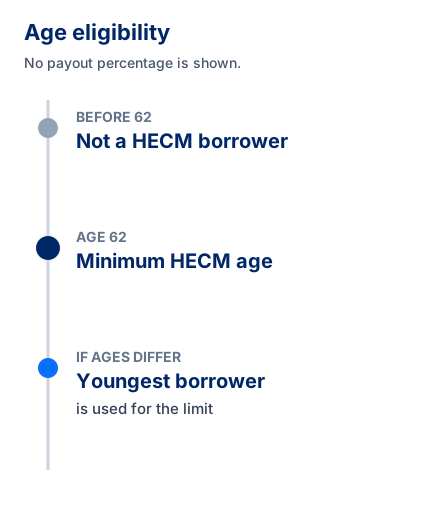
The youngest borrower sets the factor
HUD's principal limit factor uses the age of the youngest borrower and the expected interest rate. If one owner is 78 and the other borrower is 62, the calculation uses 62. Couples sometimes have to choose between putting both owners on the loan and leaving a younger spouse off. That choice has occupancy and inheritance consequences. It is a counseling topic, not a slogan.
This page does not list protections line by line. Eligible non-borrowing spouse rules depend on the case, the timing, and HUD's current requirements. Ask the HUD-approved counselor to explain how they apply before you remove someone from the application to raise the limit.
Age changes the limit. It does not set a percentage.
In the HUD factor table, an older youngest borrower generally receives a higher factor than a younger one at the same expected rate. A lower expected rate generally works in the same direction. Publishing those factors as "percent of your home you can get at 70" would be misleading, because costs and liens come out afterward and the claim amount can cap the value used.
Use the reverse mortgage calculator for a scenario, and read how much you can borrow for the rest of the inputs. The requirements overview covers occupancy, counseling, and the financial assessment that sit beside age.
Other reverse mortgages
Proprietary, sometimes called jumbo, reverse mortgages are not the HECM program. A lender may use a different minimum age. This site does not publish that age or a proceeds table for those loans. If the home's value is above the HECM claim cap, ask whether a proprietary option exists and what its age rule actually is.
Last updated 2026-10-01. This content is for education. It is not legal, tax, or financial advice and is not a commitment to lend.